Losing streaks · Risk per trade
Ten losing trades in a row: how much of your account is left?
Multiply risk per trade by the length of a losing streak and you see what a given r really costs. Four tables work through what a streak leaves you at 1% to 10% risk, the gain it takes to get back, and how rare ten losses in a row actually is, followed by steps for setting your own r. Every number comes out of a formula, not out of anyone's trading account.
Risk 5% on every trade, lose ten in a row, and 59.9% of the account is still there. That assumes each loss takes 5% of whatever was left at the time: ten trades cost 40.1% in total, and close to 60% of the money survives. The figure on its own is not frightening. Its other side is the problem: getting from 59.9% back to 100% takes a gain of 67.0%.
Two numbers get worked together here: r, the share of the account you risk on each trade, and n, the number of losses in a row. There is one formula, remaining = (1 − r)^n, and a phone calculator will rerun it. This site already has separate pieces on setting risk per trade and on how much you need to gain after a loss; the missing step was multiplying the two together.
No institutional statistics stand behind the numbers below. They all come from a few formulas, each printed next to its table. I don't forecast the market; the arithmetic only shows where ten losses in a row would leave you.
Risk per trade times losses in a row: what's left in the account
Table 1 uses remaining = (1 − r)^n. Rows are risk per trade, columns are the number of losses in a row, and each cell is the percentage of starting capital still in the account once the streak is over.
| Risk per trade (r) | 5 losses in a row | 10 in a row | 15 in a row | 20 in a row | 30 in a row |
|---|---|---|---|---|---|
| 1% | 95.1% | 90.4% | 86.0% | 81.8% | 74.0% |
| 2% | 90.4% | 81.7% | 73.9% | 66.8% | 54.5% |
| 3% | 85.9% | 73.7% | 63.3% | 54.4% | 40.1% |
| 5% | 77.4% | 59.9% | 46.3% | 35.8% | 21.5% |
| 10% | 59.0% | 34.9% | 20.6% | 12.2% | 4.2% |
Read along a row and the decay is gentle: at 1%, thirty losses in a row still leave 74.0%, and you are still in the game. Read down a column and the gap opens up. After the same ten losses, 1% leaves 90.4% and 10% leaves 34.9%. Ten wrong trades each, and one person is down less than a tenth while the other is down nearly two-thirds.
The gap comes from multiplication. 0.99 and 0.90 start 9 percentage points apart; multiply each by itself ten times and they end 55 points apart. That is why risk per trade can't be set by feel: the losses don't add up, they compound.
Risking a percentage of what's left versus a fixed amount
Table 1 never reaches zero however long the streak runs, and that property comes from how the trade is sized, not from the market. When each trade risks a fixed percentage of the current balance, the amount shrinks as the balance does: 5% of 10,000 is 500; lose it and 9,500 is left, and the next 5% is 475. The product stays above zero. The account keeps shrinking and there is always something left.
Risk a fixed amount instead and you get a different curve. Each loss is 500, the same sum every time, but it is a larger share of what remains with each one: 10% when the account is down to 5,000, 50% when it is down to 1,000. Subtraction has no floor, and a long enough streak really does end at zero.
So Table 1 only holds if you recalculate the amount from the current balance before every trade. A common habit is to work out 1% for the first trade and keep trading that same amount afterwards. For the first few trades you can't tell the difference; the further you go, the further it drifts. The sizing step itself, working back from your stop distance to a position that risks 1% of the account, is a separate calculation.
How much you need to gain to recover from ten losses in a row
Table 2 converts the ten-loss column of Table 1 into the gain needed to recover, using gain needed = 1 ÷ (1 − cumulative loss) − 1:
| Risk per trade (r) | Cumulative loss after 10 in a row | Gain needed to recover |
|---|---|---|
| 1% | 9.6% | 10.6% |
| 2% | 18.3% | 22.4% |
| 3% | 26.3% | 35.6% |
| 5% | 40.1% | 67.0% |
| 10% | 65.1% | 186.8% |
The first three rows stay in the same range, with loss and recovery only a few points apart. At 5%, a 40.1% hole takes a 67.0% gain to fill. At 10%, about 35% of the account is left and it has to gain 186.8% to get back, which means nearly tripling. The gains in the table are calculated from the unrounded remaining share; divide using the one-decimal figures shown and your answer will come out a few tenths of a point different. The curve steepens as the loss deepens because the gain has to be earned on a shrinking balance: the less that is left, the larger the percentage it takes to fill the same hole. That is the arithmetic of loss and recovery, and this table only plugs in the result of ten straight losses.
Percentages leave out one thing: time. In practice, 67.0% means winning back a whole run of trades under the same risk rules, and doing it right after ten losses in a row, when the urge to loosen those rules is strongest.
How rare is ten losses in a row?
The assumptions come first: both tables below treat every trade as independent and the win rate as fixed. Neither holds in real trading. A losing streak affects your mood, and mood affects the next few trades; market conditions tend to persist for a while, and one approach often fails again and again over the same stretch. These dependencies push the real frequency of streaks away from the figures in the tables, possibly higher, possibly lower, and the tables can't say by how much. Treat the numbers as orders of magnitude from a simplified model.
Table 3 uses (1 − p)^n and answers one question: the probability that the next n trades, the specific ones you point to, all lose.
| Win rate per trade | 5 losses in a row | 8 in a row | 10 in a row |
|---|---|---|---|
| 50% | 3.12% | 0.39% | 0.10% (about 1 in 1,024) |
| 45% | 5.03% | 0.84% | 0.25% (about 1 in 395) |
| 40% | 7.78% | 1.68% | 0.60% (about 1 in 165) |
| 35% | 11.60% | 3.19% | 1.35% (about 1 in 74) |
At a 50% win rate, ten losses in a row comes to 0.10%, about once in a thousand, which looks like somebody else's problem. But that cell is about the next ten trades, and you place far more than ten in a year. The more useful question is this: over 100 trades, what is the probability of at least one run of ten losses somewhere along the way? Table 4 answers that for three win rates under the same assumptions. No one-line formula gives it, so the figures are built up one trade at a time: keep track of how many losses in a row you are on, and carry the probabilities forward 100 times.
| Win rate per trade | Probability of at least one run of 10 losses in 100 trades |
|---|---|
| 50% | about 4.4% |
| 45% | about 10.1% |
| 40% | about 20.5% |
These three figures are rounded to one decimal place, and they come from the model, not from any record of real trades.
The 40% row is worth a second look. Take five people who each place a hundred trades at that win rate, and about one of them will run into ten losses in a row somewhere in those hundred. And a 40% win rate is not a poor result: with a large enough risk-reward ratio it makes money over time. Ten losses in a row doesn't prove a method is broken. At that win rate, it comes with the territory.
Using the tables to set your own risk per trade
Once r is fixed, each trade still has to be converted into how much to buy this time. That is the job of this site's position size calculator: enter the account total, the risk you will take on one trade, the entry price and the stop price, and it works back to a position amount.
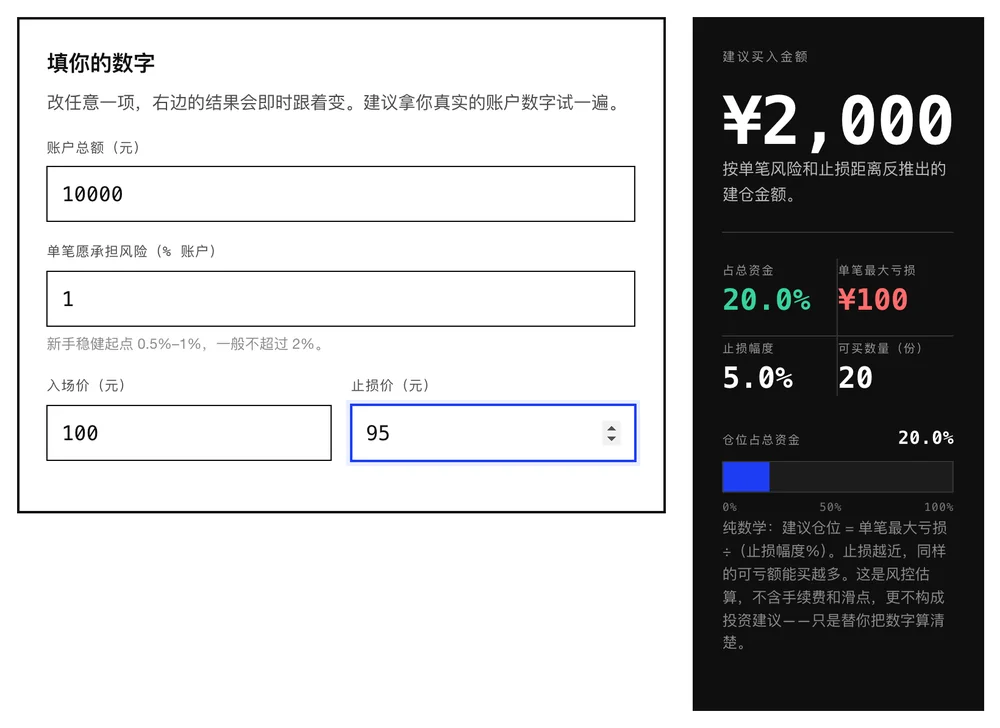
Look at how the two numbers on the right relate. The maximum loss on the trade, ¥100, is 1% of the account, while the position, ¥2,000, is 20% of it. How much you buy and the most you can lose on the trade are two different numbers. The first changes with how far away the stop is; the second is the r in Table 1. The tighter the stop, the more the same r lets you buy, and the more often you get stopped out, so the count of losses in a row climbs faster.
In practice, the steps run in roughly this order:
- Write down a specific amount: how far the account can fall after a losing streak with you still willing to open the next trade as planned. An amount, not a percentage.
- Pick a streak length to design for. If you don't know your win rate, prepare for the worst row of Table 3 (35%), where ten losses in a row comes to 1.35%.
- Go back to Table 1 and find the matching row. If you design for ten losses in a row with a floor of 80% left, 2% leaves 81.7% and 3% leaves 73.7%, so r falls between those two rows, and you take the smaller.
- Check it against Table 2: at 2%, ten losses in a row need a 22.4% gain to recover. How many trades, and how long, does a gain like that take with your approach? If you can't answer, go down another step.
- Recalculate the amount from the current balance before every trade. Skip this and the first four steps were wasted.
Run it yourself For any combination the tables leave out, one pass through the formulas gives it: remaining = (1 − r)^n, gain needed = 1 ÷ remaining − 1. At the very least, put in the r you actually use today and work out ten losses in a row.
The percentages in the tables were chosen to make the arithmetic clear, and copying them gets you nothing. What matters is that the r you trade with was worked out, and that you know where ten losses in a row would take you.
Common questions
How do I count ten losses in a row? Does a small win in the middle break the streak?
Count by closed result: each losing trade adds one, and any winning trade resets the count to zero. The awkward ones are the break-even trades, where the result after fees is only a tiny amount either way. Whether a trade like that breaks the streak is a call you have to make once and keep for the whole year. If the convention drifts, the streak lengths you count drift with it.
I haven't started trading yet. How do I know my win rate?
You don't. The win rates in Tables 3 and 4 are assumed values plugged in for the arithmetic; nobody measured them. The only way to get your own number is to place a batch of trades at a size small enough that losing all of it wouldn't matter, then count. Until then, preparing for the worst row in the table is safer than preparing for the best.
Do I need to convert the table figures into the real amounts in my account?
The tables are all ratios; multiply by your capital and you have amounts. One thing they leave out is fees and slippage. Each actual loss will be a little larger than the planned r, and the more often you trade, the more that shows. To stay close to reality, record r from the actual loss once the trade has closed, not from the stop distance you planned when you placed the order.
Do these tables still work with futures and leverage?
The formulas don't care about the instrument. They only look at what percentage of the account each trade loses. Leverage makes that actual loss harder to control: a gap, slippage or a liquidation can each push one trade's loss past the r you set, and the excess isn't in the tables. With leverage, Table 1 shows the optimistic side.
Risk note
Arithmetic only: this is not investment advice and it recommends no specific asset. Crypto prices are extremely volatile and losing all of your capital is possible. The percentages, streak lengths and win rates here are assumed values set out to explain the formulas; they are nobody's trading record and they predict no gain or loss. The two streak-probability tables rest on every trade being independent and the win rate being fixed, and neither condition holds in real markets. How much to risk per trade, and how long a losing streak has to run before you stop, are yours to decide, and the consequences are yours too.